Cashew
New PurchaseRefinance PrivateRefinance HDB
LoginGet started
Cashew

We make the mortgage process simple, transparent, and tailored to your needs.

Quick Links

  • Home Valuation
  • Rent or Buy
  • Equity Term Loan
  • Home Loan Quote
  • Home Loan Rates
  • HDB Loan Rates
  • Condo Loan Rates
  • Commercial Loan Rates
  • SORA Rates
  • Refinance Your Home Loan
  • Access by Cashew
  • Mortgage Eligibility Report
  • Mortgage Guide

Tools & Resources

  • Cashew Academy
  • Refer a Friend
  • AI Assistant
  • Calculators
  • Resources
  • Partner Banks
  • Conveyancing Lawyers
  • Properties by District
  • Property Directory
  • Managing Agents
  • Our Partners
  • Compare Brokers

Cashew Mortgages

  • +65 8021 7460·WhatsApp
  • 400 Orchard Road #18-08
    Singapore 238875

  • Meet the Consultants
  • About Us
  • Careers
  • >_MCP
  • Contact Us

© 2026 Cashew. All rights reserved.

Terms of ServicePrivacy Policy
Cashew
New PurchaseRefinance PrivateRefinance HDB
LoginGet started
Cashew

We make the mortgage process simple, transparent, and tailored to your needs.

Quick Links

  • Home Valuation
  • Rent or Buy
  • Equity Term Loan
  • Home Loan Quote
  • Home Loan Rates
  • HDB Loan Rates
  • Condo Loan Rates
  • Commercial Loan Rates
  • SORA Rates
  • Refinance Your Home Loan
  • Access by Cashew
  • Mortgage Eligibility Report
  • Mortgage Guide

Tools & Resources

  • Cashew Academy
  • Refer a Friend
  • AI Assistant
  • Calculators
  • Resources
  • Partner Banks
  • Conveyancing Lawyers
  • Properties by District
  • Property Directory
  • Managing Agents
  • Our Partners
  • Compare Brokers

Cashew Mortgages

  • +65 8021 7460·WhatsApp
  • 400 Orchard Road #18-08
    Singapore 238875

  • Meet the Consultants
  • About Us
  • Careers
  • >_MCP
  • Contact Us

© 2026 Cashew. All rights reserved.

Terms of ServicePrivacy Policy
All resources

Category

Refinancing & Cost Savings

Refinancing your home loan in Singapore can lead to significant savings, especially as bank loan rates have dropped well below the HDB concessionary rate of 2.6%. Whether you are considering switching from an HDB loan to a bank loan, comparing refinancing versus repricing, or timing your move around lock-in periods and property market shifts, understanding the costs, trade-offs, and process is essential to making the right decision. Historical data shows bank loans have been cheaper than HDB loans roughly 76% of the time over the past 20 years, making refinancing one of the most impactful financial moves a homeowner can make.

16 articles

Refinancing & Cost Savings

Reprice, refinance, or wait? A breakeven test for 2026 borrowers

The right choice between repricing, refinancing, or waiting depends on the gap between your contracted rate and current market rates, whether a lock-in or clawback penalty is still active, and how large your outstanding loan balance is. Repricing with your existing bank is cheap and fast but usually offers a smaller rate cut, refinancing to a new bank unlocks the biggest savings but involves upfront costs and notice periods, and waiting makes sense only when penalties outweigh the potential savings. Borrowers who locked in near the end-2023 rate peak and are past their lock-in period stand to benefit the most from switching now.

Sarah Chen·18 Aug 2026
Cashew

We make the mortgage process simple, transparent, and tailored to your needs.

Quick Links

  • Home Valuation
  • Rent or Buy
  • Equity Term Loan
  • Home Loan Quote
  • Home Loan Rates
  • HDB Loan Rates
  • Condo Loan Rates
  • Commercial Loan Rates
  • SORA Rates
Refinancing & Cost Savings

Still on a 3.5% loan? The 2026 refinancing math, and how to sequence it

If you locked in a mortgage during the 2022 to 2024 rate spike, you are likely still paying 3.5% or more, while current fixed rates sit around 1.4% to 1.6%, making refinancing the highest-impact financial move available to most Singapore homeowners. To capture the saving without penalties, start the process four months before your lock-in ends, confirm you pass the TDSR stress test at 4.0%, and compare packages across multiple banks before committing.

Sarah Chen·3 Aug 2026
Refinancing & Cost Savings

Your rate dropped from 2.8% to 1.6%. Why does the monthly instalment barely move?

When mortgage rates fall, the monthly instalment drops only modestly because it bundles both interest and principal repayment together. The rate change only affects the interest portion, while the principal portion stays the same, diluting the visible impact. Looking at total interest paid or the outstanding balance at the end of a lock-in period gives a far more accurate picture of the true saving.

Sarah Chen·25 Jul 2026
Refinancing & Cost Savings

2Y at 1.4% or 3Y at 1.6%? How to price the bet on where rates land in 2028

When choosing between a 2-year fix at 1.4% and a 3-year fix at 1.6% on a S$2 million loan, the decision comes down to whether two-year fixed rates in late 2028 will exceed 2.0%, which is the break-even point where total interest costs are equal across both paths. The 2-year fix is the more defensible default for borrowers without a strong view on rising rates, as it costs less upfront and preserves the option to reprice with better information in 2028. The 3-year fix only earns its premium if you genuinely expect rates to rise above 2.0% or if the added certainty is worth the extra cost to you.

Sarah Chen·20 Jul 2026
Refinancing & Cost Savings

The HDB loan isn't always the safe choice, especially if you're selling soon

The HDB concessionary loan offers stability and flexibility, but if you plan to sell within a few years, a fixed bank loan at a lower rate can result in significant interest savings. The key is securing a package with a sale waiver clause that removes early redemption penalties when you sell, otherwise the penalty can wipe out those savings. Choose the HDB loan if your timeline is uncertain, and consider a bank loan only if you have a firm exit plan and the right package conditions.

Sarah Chen·14 Jun 2026
Refinancing & Cost Savings

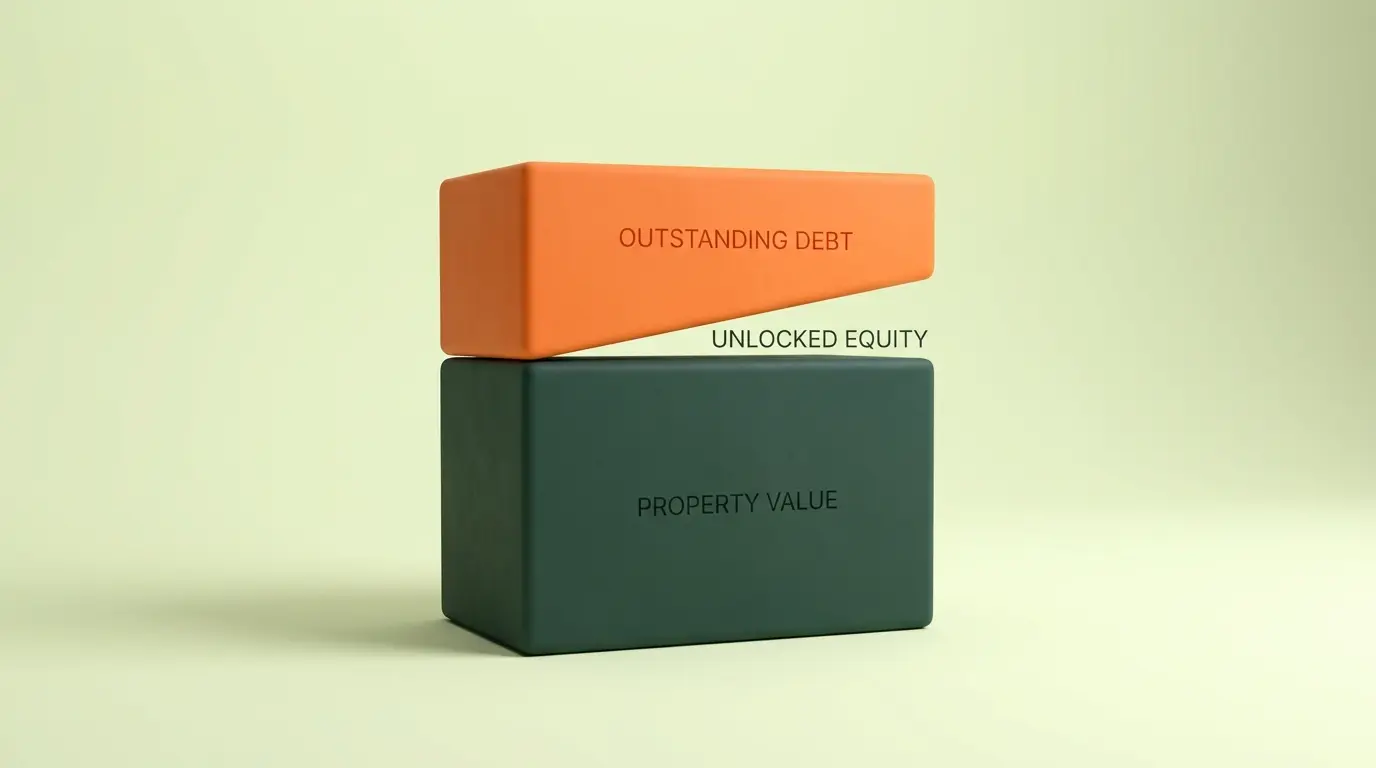
How much equity can you unlock?

You can unlock equity from your private property without selling by taking an equity term loan, which is secured against your home and priced at mortgage rates rather than personal loan rates. The amount you can withdraw is calculated by taking 75% of your property's current valuation, then subtracting your outstanding loan and any CPF principal and accrued interest used. Cashew's free equity term loan estimator shows you your real withdrawable cash in seconds, with no sign-up or personal details required.

Sarah Chen·8 Jun 2026
Refinancing & Cost Savings

What's your home worth today?

Your home's current value drives every major financial decision tied to your property, from refinancing eligibility and loan-to-value ratios to selling price and equity access. Cashew's free home valuation tool gives you an indicative value in seconds by entering your postal code and unit number, with no sign-up required. The estimate is powered by Amicus, using the same automated valuation model banks rely on, and connects directly to relevant loan packages, a mortgage calculator, and an affordability check.

Sarah Chen·8 Jun 2026
Refinancing & Cost Savings

From lock-in tracking to rate negotiation: what active borrowers do differently

Active mortgage borrowers in Singapore protect themselves by tracking their lock-in expiry date, running a break-even calculation before refinancing, and collecting term sheets from multiple banks before accepting any offer. Borrowers who skip these steps often roll onto higher reversion rates unnoticed or accept packages without knowing whether a better rate was available. The difference between paying more and paying less is not financial expertise but a small number of deliberate actions taken at the right time.

Sarah Chen·21 May 2026
Refinancing & Cost Savings

HDB's 2026 MOP wave: what the supply surge means for your refinancing and upgrade plans

A large wave of HDB flats reaching their Minimum Occupation Period in 2026, combined with the government exceeding its BTO supply targets, is creating a buyer-friendly resale market with softening prices. For buyers, this means more negotiating room and lower loan requirements. For upgraders and refinancers, it requires careful timing and a fresh look at current valuations before assuming previous numbers still apply.

Sarah Chen·8 May 2026
Refinancing & Cost Savings

When Does Refinancing an HDB Loan Make Sense? A Data-Driven Guide with Kevin Learns Investing

Mortgage rates in Singapore are at historic lows, making refinancing from an HDB loan to a bank loan tempting. But the switch is permanent and involves trade-offs. Understand when refinancing makes sense and when to stay put.

Sarah Chen·6 Jan 2026
Refinancing & Cost Savings

Chris Chong (HoneyMoneySG) Saved S$6,000 Refinancing His HDB Loan: Here's How

Financial blogger Chris Chong (HoneyMoneySG) successfully reduced his mortgage interest rate from 2.6% (HDB loan) to a 1.8% fixed bank loan, leading to a net savings of approximately S$6,000 over three years. If you are an HDB homeowner, you could be overpaying: check the best available rates on Cashew or contact a Cashew advisor today to see how much you could potentially save.

Sarah Chen·10 Nov 2025
Refinancing & Cost Savings

20 Years of Data Prove It: Bank Loans Beat HDB Loans

Over the last two decades, HDB’s 2.6% home loan rate has stayed rock solid, while SORA-based bank loans have floated up and down with the market. But when you crunch 20 years of data, a clear pattern emerges: despite a few short spikes, bank loans have been cheaper almost 80% of the time. A borrower with a $500,000 loan over 20 years would have saved roughly $70,000 by going with a typical SORA + 0.5% bank package instead of sticking with HDB’s fixed rate. The takeaway? Start safe with an HDB loan when buying your BTO, but once you’ve collected your keys, refinance to a bank loan and let the data work in your favour.

Sarah Chen·15 Oct 2025
Page 1 of 2Next
  • Refinance Your Home Loan
  • Access by Cashew
  • Mortgage Eligibility Report
  • Mortgage Guide
  • Tools & Resources

    • Cashew Academy
    • Refer a Friend
    • AI Assistant
    • Calculators
    • Resources
    • Partner Banks
    • Conveyancing Lawyers
    • Properties by District
    • Property Directory
    • Managing Agents
    • Our Partners
    • Compare Brokers

    Cashew Mortgages

    • +65 8021 7460·WhatsApp
    • 400 Orchard Road #18-08
      Singapore 238875

    • Meet the Consultants
    • About Us
    • Careers
    • >_MCP
    • Contact Us

    © 2026 Cashew. All rights reserved.

    Terms of ServicePrivacy Policy
    Cashew
    New PurchaseRefinance PrivateRefinance HDB
    LoginGet started
    AllAffordability & Financial PlanningHome Buying 101Rate UpdatesMortgage Basics & FAQsRefinancing & Cost SavingsRegulations & PolicyTech & ToolsAdvisor HubHomeowner