Cashew
New PurchaseRefinance PrivateRefinance HDB
LoginGet started
Cashew

We make the mortgage process simple, transparent, and tailored to your needs.

Quick Links

  • Home Valuation
  • Rent or Buy
  • Equity Term Loan
  • Home Loan Quote
  • Home Loan Rates
  • HDB Loan Rates
  • Condo Loan Rates
  • Commercial Loan Rates
  • SORA Rates
  • Access by Cashew
  • Mortgage Eligibility Report
  • Mortgage Guide

Tools & Resources

  • Cashew Academy
  • Refer a Friend
  • AI Assistant
  • Calculators
  • Resources
  • Partner Banks
  • Conveyancing Lawyers
  • Properties by District
  • Property Directory
  • Managing Agents
  • Our Partners
  • Compare Brokers

Cashew Mortgages

  • +65 8021 7460
  • 400 Orchard Road #18-08
    Singapore 238875

  • Meet the Consultants
  • About Us
  • Careers
  • >_MCP
  • Contact Us

© 2026 Cashew. All rights reserved.

Terms of ServicePrivacy Policy
Cashew
New PurchaseRefinance PrivateRefinance HDB
LoginGet started

Resources

Make sense of your mortgage.

Expert guides, market insights, and tools for every stage of your home financing journey.

20 Years of Data Prove It: Bank Loans Beat HDB Loans
Refinancing & Cost Savings

20 Years of Data Prove It: Bank Loans Beat HDB Loans

Over the last two decades, HDB’s 2.6% home loan rate has stayed rock solid, while SORA-based bank loans have floated up and down with the market. But when you crunch 20 years of data, a clear pattern emerges: despite a few short spikes, bank loans have been cheaper almost 80% of the time. A borrower with a $500,000 loan over 20 years would have saved roughly $70,000 by going with a typical SORA + 0.5% bank package instead of sticking with HDB’s fixed rate. The takeaway? Start safe with an HDB loan when buying your BTO, but once you’ve collected your keys, refinance to a bank loan and let the data work in your favour.

Sarah Chen·15 Oct 2025

Editor’s picks

Hand-picked reads for you

Home Buying 101

Does HDB check your credit report for a BTO? What actually happens before key collection

HDB checks your credit report during the HFE letter application, where it retrieves your CBS credit report in the background using your consent. The loan amount is then reassessed again before key collection, so changes in income or debt during the BTO waiting period can reduce the loan you qualify for. A Debt Management Programme does not automatically disqualify you but reduces your borrowing capacity through its impact on your MSR and TDSR.

Sarah Chen·15 Jul 2026
Cashew

We make the mortgage process simple, transparent, and tailored to your needs.

Quick Links

  • Home Valuation
  • Rent or Buy
  • Equity Term Loan
  • Home Loan Quote
  • Home Loan Rates
  • HDB Loan Rates
  • Condo Loan Rates
  • Commercial Loan Rates
  • SORA Rates
Home Buying 101

BTO vs Resale HDB 2026: Which Is the Smarter Buy?

With 19,600 new BTO flats and ~13,500 MOP units flooding the market in 2026, first-time buyers face a genuine choice—and the right pick could save S$78,000+ over the life of a loan.

Sarah Chen·22 Mar 2026
Refinancing & Cost Savings

How much equity can you unlock?

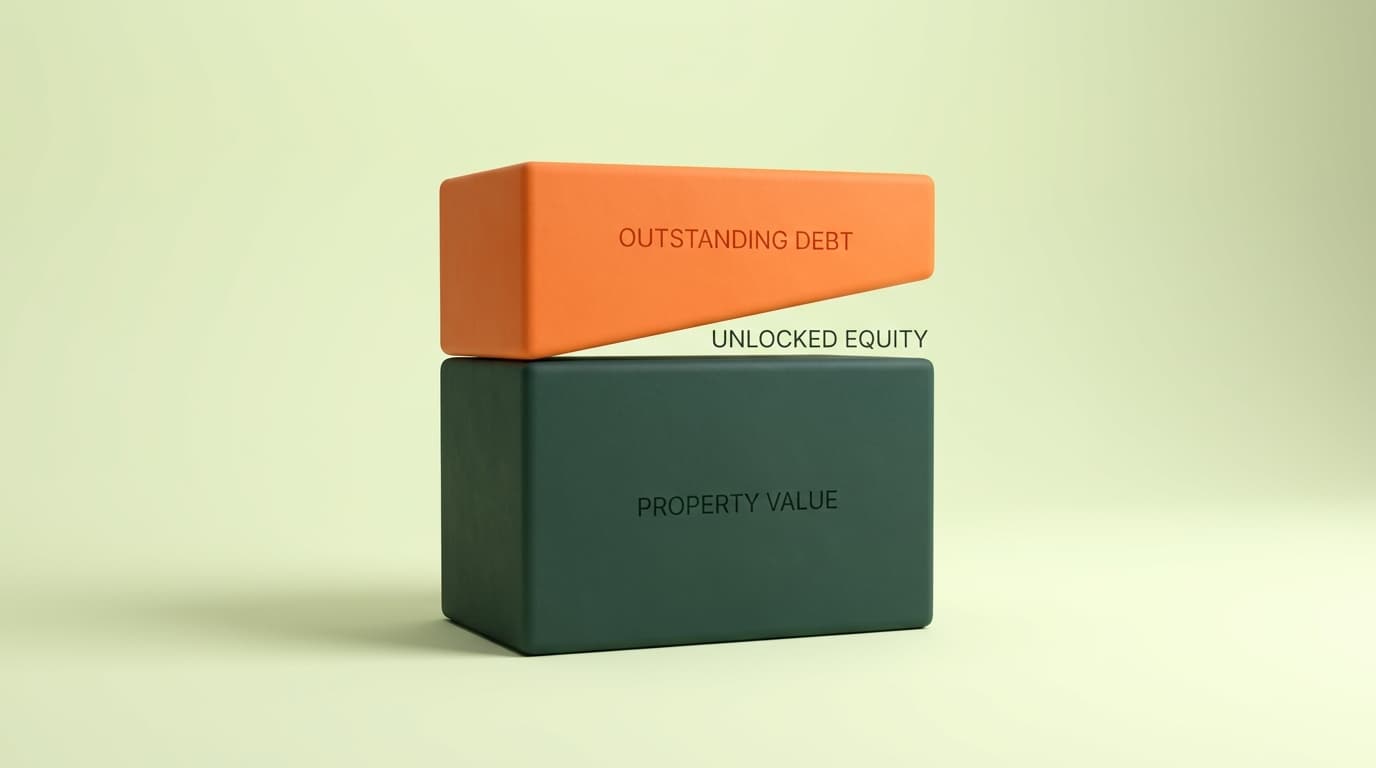
You can unlock equity from your private property without selling by taking an equity term loan, which is secured against your home and priced at mortgage rates rather than personal loan rates. The amount you can withdraw is calculated by taking 75% of your property's current valuation, then subtracting your outstanding loan and any CPF principal and accrued interest used. Cashew's free equity term loan estimator shows you your real withdrawable cash in seconds, with no sign-up or personal details required.

Sarah Chen·8 Jun 2026

Latest

View all
Affordability & Financial Planning

The 12-month rule that shrinks your housing grant

HDB calculates EHG based on average gross monthly household income over a 12-month window, but each person's income is averaged only over the months they actually worked, not spread across all 12 months. This means short stints of part-time or contract work count at full monthly value rather than being diluted, which can push a household into a lower income band and significantly reduce the grant amount.

Sarah Chen·4 Oct 2026
Affordability & Financial Planning

Before you put your name on your parents' flat, do this sum

Before adding your name to a parent's HDB flat, calculate the ABSD and LTV impact on your own future property purchase, since becoming an owner (even unintentionally via joint tenancy or inheritance) can add S$300,000 in stamp duty and, if a loan is attached, push LTV limits down enough to raise required upfront cash by up to S$750,000. All five main options for handling a parent's flat (leaving it vacant, renting it out, right-sizing, Lease Buyback, or selling) remain neutral for an adult child's own property plans only if that child stays off the title, so securing an LPA early and verifying CPF refund amounts and title arrangements are essential first steps.

Sarah Chen·2 Oct 2026
Rate Updates

DBS's New CPF-OA HDB Loan, Explained

Cashew·1 Oct 2026
  • Access by Cashew
  • Mortgage Eligibility Report
  • Mortgage Guide
  • Tools & Resources

    • Cashew Academy
    • Refer a Friend
    • AI Assistant
    • Calculators
    • Resources
    • Partner Banks
    • Conveyancing Lawyers
    • Properties by District
    • Property Directory
    • Managing Agents
    • Our Partners
    • Compare Brokers

    Cashew Mortgages

    • +65 8021 7460
    • 400 Orchard Road #18-08
      Singapore 238875

    • Meet the Consultants
    • About Us
    • Careers
    • >_MCP
    • Contact Us

    © 2026 Cashew. All rights reserved.

    Terms of ServicePrivacy Policy
    RefinancingFirst-time buyerFixed vs floatingHDB loan

    Browse by topic

    Browse all articles
    • 01

      Affordability & Financial Planning

      Make smarter decisions before you buy. Learn how much you can really afford, how to optimise your CPF and cash savings, and how to plan your finances to stay within MSR, TDSR, and LTV limits. · 32 articles

    • 02

      Home Buying 101

      Home Buying 101 is a comprehensive resource covering every stage of the Singapore home purchase journey, from choosing between BTO, resale HDB, and private condo to understanding mortgage rates, grants, stamp duties, and eligibility rules. It includes practical guides on affordability checks, common first-timer mistakes, and how to navigate the 2026 BTO launch pipeline and refinancing environment. · 29 articles

    • 03

      Rate Updates

      Rate Updates is your always-on feed for Singapore home-loan interest rates. Each update delivers fresh rate tables, concise market commentary, and data-driven insights—so buyers and refinancers can spot opportunities, time their decisions, and lock in the best deals with confidence. · 14 articles

    • 04

      Mortgage Basics & FAQs

      This section covers the essentials of Singapore home loans, including current condo mortgage rates, fixed vs floating rate comparisons, HDB loan refinancing, how to choose the best home loan step by step, and answers to common questions on topics like CPF usage, TDSR, MSR, lock-in periods, and loan eligibility. Whether you are a first-time buyer or looking to refinance, these guides help you understand your options and make informed mortgage decisions. Cashew simplifies the process by comparing 500+ live packages across all major banks, with a Best Rate Guarantee and fully digital application. · 15 articles

    • 05

      Refinancing & Cost Savings

      Refinancing your home loan in Singapore can lead to significant savings, especially as bank loan rates have dropped well below the HDB concessionary rate of 2.6%. Whether you are considering switching from an HDB loan to a bank loan, comparing refinancing versus repricing, or timing your move around lock-in periods and property market shifts, understanding the costs, trade-offs, and process is essential to making the right decision. Historical data shows bank loans have been cheaper than HDB loans roughly 76% of the time over the past 20 years, making refinancing one of the most impactful financial moves a homeowner can make. · 17 articles

    • 06

      Regulations & Policy

      This section covers regulations and policies relevant to Singapore mortgage advisory, including rules governing home loans, lending limits, and borrower eligibility. · 27 articles

    • 07

      Advisor Hub

      The Advisor Hub is a resource centre for mortgage advisors using ACCESS by Cashew. It covers how to read standardised mortgage factsheets, create and share custom client proposals, submit bank applications, and use the built-in mortgage calculator to estimate payments and compare packages. · 5 articles

    • 08

      Tech & Tools

      Explore how Cashew’s tech makes home financing easier. From AI-powered tools to smart calculators, learn how to get personalised advice, instant insights, and better decisions — all without picking up the phone. · 3 articles