For many Singaporean homeowners, the HDB Concessionary Loan is the default choice. Its 2.6% interest rate, pegged 0.1% above the CPF Ordinary Account rate, has been a pillar of stability for decades.
However, with market interest rates dropping, is the default 2.6% always the best financial decision?
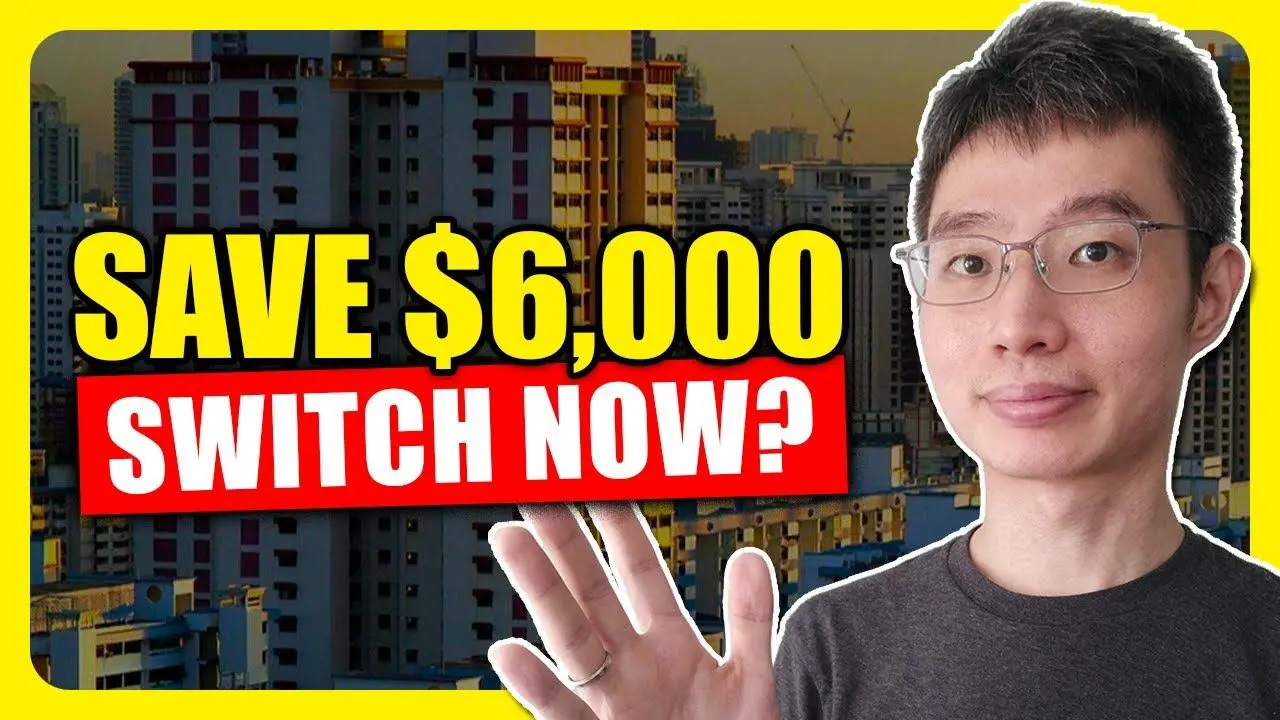
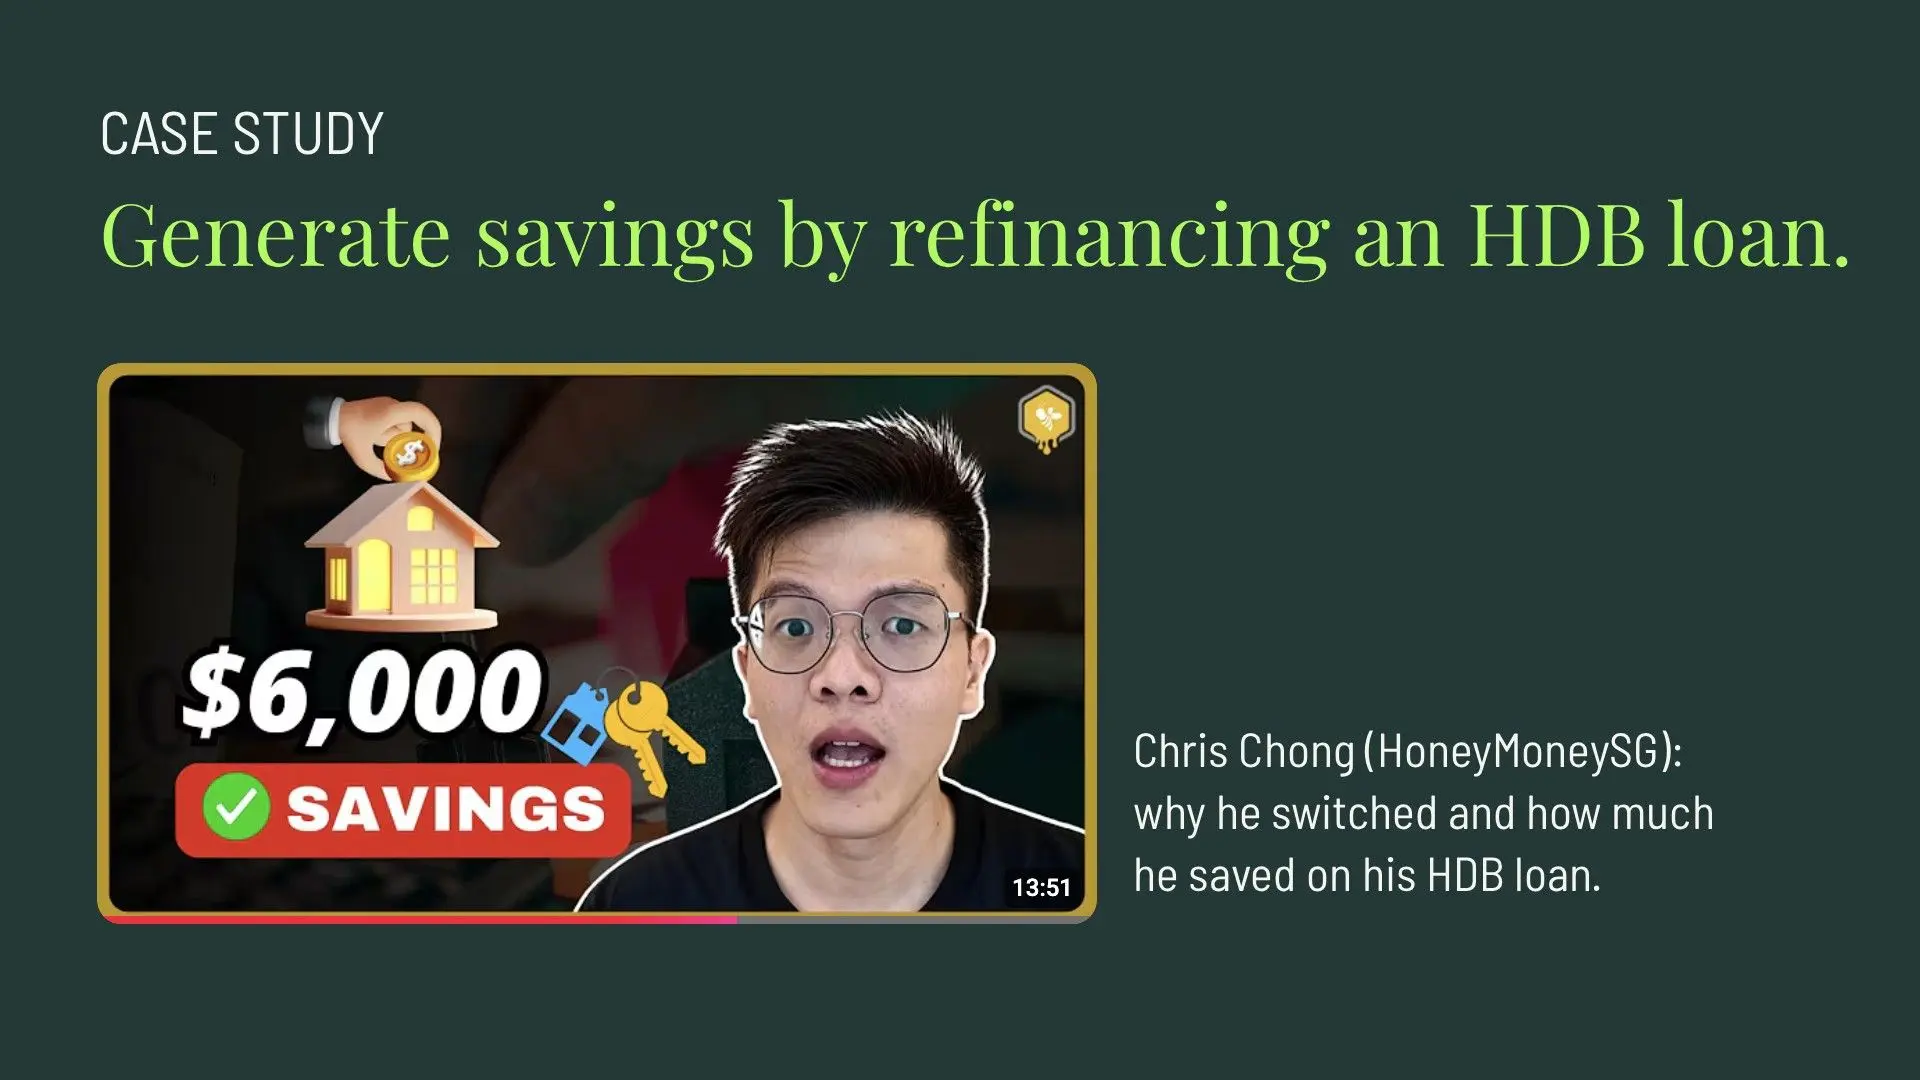
We recently analyzed a detailed video from financial blogger Chris Chong (HoneyMoneySG), who documented his personal journey of refinancing from his HDB loan to a bank loan. His experience provides a practical, real-world case study on the "why," "how," and "how much" of refinancing.
Read on for our summary or watch his video on YouTube.
The Homeowner's Profile & Initial Situation
To understand the decision, it's important to know the starting point.
-
Property: HDB BTO, keys collected in 2024.
-
Initial Loan: HDB Concessionary Loan at 2.6%.
-
Outstanding Mortgage: Approximately S$230,000.
-
Remaining Tenor: 24 years.
-
Key Constraint: The 5-year Minimum Occupation Period (MOP) ends in 2029. Any new loan package should ideally fit within this timeline.
Like many new homeowners, he initially took the HDB loan. This allowed the downpayment to be paid fully via CPF. He then waited about a year for bank loan rates to become more favorable before deciding to make a switch.
The "Why": Timing, Motivation, and Opportunity Cost
The primary motivator was the falling interest rate environment. The homeowner realized that by staying at 2.6%, he was "overpaying" compared to the current bank rates available.
A key part of his analysis was the opportunity cost of waiting. While some may try to time the market to catch the absolute lowest rate, he argued that every month spent paying 2.6% is a cost in itself. He felt the rates were already low enough to justify making the move, as the refinancing process itself can take a few months to finalize.
The "How": Choosing the Right Package
The homeowner compared two main types of bank loans: floating and fixed.
-
Floating rates are typically tied to the SORA (Singapore Overnight Rate Average) plus a bank's spread.
-
Fixed rates lock in a specific rate for a set period (e.g., 2-3 years) before reverting to a floating rate.
Given his MOP constraint, he opted for a 3-year fixed rate at 1.8%. This provided him with rate stability and predictability for the majority of his remaining MOP.
Interestingly, he also made two other strategic moves:
-
Stretched Loan Tenor: He extended his remaining loan tenor from 24 to 27 years. This lowered his monthly cash outflow, aligning with his financial philosophy of using low-cost "good debt" to optimize cash flow.
-
Sourced Extra Perks: The bank loan he chose also qualified him for a separate cashback bonus (in his case, with his POSB savings account), which further reduced his net interest paid.
The Numbers: A Real-World Savings Calculation
This is where the decision becomes clear.
| Metric | Before (HDB Loan) | After (Bank Loan) |
|---|
| Interest Rate | 2.6% | 1.8% (Fixed for 3 years) |
| Loan Tenor | 24 years remaining | 27 years remaining |
| Monthly Instalment | ~S$1,102 | ~S$920 |
The Result:
Even after accounting for legal and valuation fees (which are common for smaller loan quantums), the homeowner calculated his net benefit to be around S$6,000 over the 3-year fixed period, not including the additional bank cashback bonus.
Is Sticking with an HDB Loan Ever a Good Idea?
To maintain an objective view, the video also fairly presents the case for not refinancing. The HDB loan has clear benefits:
-
No Lock-In: You can make partial or full repayments at any time without penalty.
-
No Fees: There are no legal or valuation fees to set up.
-
Simplicity: For those with very small loan amounts (e.g., under S$200,000), the net savings after fees might not be substantial enough to justify the effort.
Ultimately, it's a trade-off. The "peace of mind" from an HDB loan comes at the cost of a higher interest rate in the current market.
Key Takeaways for Homeowners
This case study demonstrates that for many HDB owners, the default 2.6% loan may not be the most financially optimal choice right now.
As the homeowner's journey shows, refinancing from an HDB loan to a bank loan can result in significant monthly savings and a lower overall cost of borrowing. The key is to run the numbers based on your specific situation.
If this analysis resonates with you, your next step is to see what's possible. Don't continue overpaying on your mortgage by sticking to the default. Take action by checking the best available rates on Cashew to see your potential savings. For personalized, end-to-end advice, contact a Cashew advisor today for a clear, data-driven mortgage plan.
 Sarah Chen
 Sarah Chen29 Aug 2025