Cashew
New PurchaseRefinance PrivateRefinance HDB
LoginGet started
Cashew

We make the mortgage process simple, transparent, and tailored to your needs.

Quick Links

  • Home Valuation
  • Rent or Buy
  • Equity Term Loan
  • Home Loan Quote
  • Home Loan Rates
  • HDB Loan Rates
  • Condo Loan Rates
  • Commercial Loan Rates
  • SORA Rates
  • Refinance Your Home Loan
  • Access by Cashew
  • Mortgage Eligibility Report
  • Mortgage Guide

Tools & Resources

  • Cashew Academy
  • Refer a Friend
  • AI Assistant
  • Calculators
  • Resources
  • Partner Banks
  • Conveyancing Lawyers
  • Properties by District
  • Property Directory
  • Managing Agents
  • Our Partners
  • Compare Brokers

Cashew Mortgages

  • +65 8021 7460·WhatsApp
  • 400 Orchard Road #18-08
    Singapore 238875

  • Meet the Consultants
  • About Us
  • Careers
  • >_MCP
  • Contact Us

© 2026 Cashew. All rights reserved.

Terms of ServicePrivacy Policy
Cashew
New PurchaseRefinance PrivateRefinance HDB
LoginGet started
ResourcesRefinancing & Cost Savings

20 Years of Data Prove It: Bank Loans Beat HDB Loans

Sarah ChenSarah Chen
•Updated 13 Nov 2026•4 min read
20 Years of Data Prove It: Bank Loans Beat HDB Loans

Singapore home buyers have a simple choice: take an** HDB loan** (fixed at 2.6%) or a bank loan, available with floating and fixed rate.

The HDB rate has been unchanged at 2.6% since 1999, set 0.1 percentage points above the CPF Ordinary Account (OA) interest rate of 2.5%. Bank loans, by contrast, move with market rates — usually 3-month compounded SORA + a spread.

With 20 years of SORA data now available (since its introduction in 2005), we can finally compare how both options have really performed.

The Long View: When Were Bank Loans Actually More Expensive?

The chart below tells the story clearly.

  • The red line shows the constant 2.6% HDB rate.

  • The green line tracks the 3-month compounded SORA + 0.5%, the realistic cost of a typical floating bank loan.

  • The blue line is the raw 3-month SORA itself.
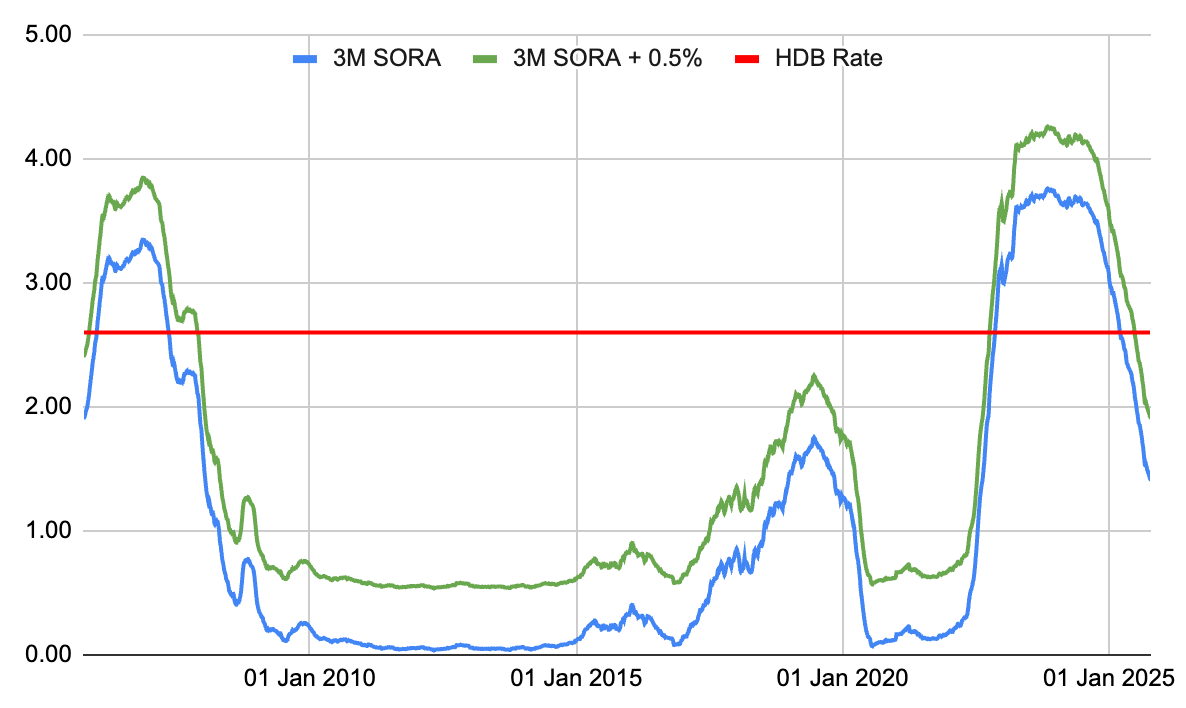
Source: 3-months compounded SORA by MAS

Across the full 20-year period (2005 – 2025):

  • Bank loans were cheaper than HDB loans for 182 out of 240 months.

  • Only two periods saw bank rates exceed 2.6% — from 2005 to 2007, and again 2023 to 2024 during the global rate spike.

That means roughly 76% of the time, borrowers with bank loans enjoyed lower interest rates.

The Difference in Dollars: $70,000 Saved

Let’s put that in concrete terms.

If you borrowed S$500,000 in 2005 for 20 years, here’s what would have happened:

Loan TypeAverage RateTotal Repaid (20 yrs)Interest PaidDifference
HDB LoanConstant 2.6%≈ S$642,000≈ S$142,000–
Bank Loan (3M SORA + 0.5%)Variable (typically 1–2.5%)≈ S$572,000≈ S$72,000≈ S$70,000 less

So while both loans have their merits, bank borrowers paid about S$70,000 less in total interest over the same 20-year period.

What About Fixed-Rate Bank Loans?

Even if you had chosen a fixed-rate bank loan instead of a floating one, the overall outcome would have been very similar. That’s because fixed-rate packages in Singapore are ultimately priced off the same SORA benchmark — the bank simply “locks in” a rate (for example, 2.00%, representing SORA plus a spread) for a limited period.

In other words, fixed-rate loans don’t operate in a different universe — they’re just temporary shields against short-term rate movements. Over a 20-year tenure, a borrower will typically refinance several times, so the long-term cost difference between fixed and floating packages is usually minimal. The main advantage of a fixed rate is short-term stability, not necessarily a lower total cost.

Why HDB Loans Still Make Sense — At First

HDB loans offer unbeatable convenience, especially for first-time BTO buyers:

  • No cash downpayment (you can use CPF fully)

  • Lower upfront income and credit requirements

That’s why it’s smart to start with an HDB loan when buying your first BTO flat.

It lets you secure your home safely while construction completes — often over 3–5 years.

Why Refinancing to a Bank Loan Is the Smarter Long-Term Move

Once you’ve collected your keys, your loan formally begins, and that’s the perfect time to refinance to a bank loan.

Here’s why:

  1. Lower interest rate potential: Banks typically price at SORA + 0.5–0.8%, which historically stays below 2.6%.

  2. Flexible packages: You can choose fixed, floating, or hybrid structures to match your financial comfort.

  3. Refinancing promotions: Banks often offer legal subsidies or cash rebates to attract refinancers.

  4. Compounding savings: Even a 0.5% difference on a 20-year loan can mean tens of thousands saved.

In short, HDB loans are a good starting point, but bank loans win the long game.

The Takeaway

Over the last 20 years, a borrower with a bank loan tied to 3-month SORA + 0.5% would have saved around S$70,000 versus staying with an HDB loan at 2.6%.

While past performance isn’t a guarantee of future rates, the data shows that refinancing after key collection can be one of the most impactful financial decisions a homeowner makes.
Cashew

We make the mortgage process simple, transparent, and tailored to your needs.

Quick Links

  • Home Valuation
  • Rent or Buy
  • Equity Term Loan
  • Home Loan Quote
  • Home Loan Rates
  • HDB Loan Rates
  • Condo Loan Rates
  • Commercial Loan Rates
  • SORA Rates

Thinking of switching banks? Compare today's refinancing rates from all major banks.


Sarah Chen

Sarah Chen

Sarah is a senior mortgage advisor with over 10 years of experience in Singapore's property market.

Share this article

Related Articles

Refinancing & Cost Savings

Refinancing vs. Repricing: How to Save on Your Mortgage

When your home loan’s interest rate is no longer competitive, you have two main options – refinance with a different bank, or reprice with your existing bank. What’s the difference, and which will save you more? In this article, we break down refinancing vs. repricing, comparing the pros, cons, and cost savings of each. By understanding these two routes, you can choose the best strategy to reduce your mortgage interest and keep more money in your pocket.

Sarah Chen·29 May 2025
Refinancing & Cost Savings

Falling Home Loan Rates Could Save Singaporeans Thousands — If They Take Action

Home loan rates in Singapore have fallen to nearly half of last year’s levels, yet many homeowners remain stuck on costly packages. Experts warn that failing to refinance could mean losing out on savings of up to $12,000 a year.

Sarah Chen·29 Aug 2025
Refinancing & Cost Savings

Chris Chong (HoneyMoneySG) Saved S$6,000 Refinancing His HDB Loan: Here's How

Financial blogger Chris Chong (HoneyMoneySG) successfully reduced his mortgage interest rate from 2.6% (HDB loan) to a 1.8% fixed bank loan, leading to a net savings of approximately S$6,000 over three years. If you are an HDB homeowner, you could be overpaying: check the best available rates on Cashew or contact a Cashew advisor today to see how much you could potentially save.

Sarah Chen·10 Nov 2025
Refinancing & Cost Savings

When Does Refinancing an HDB Loan Make Sense? A Data-Driven Guide with Kevin Learns Investing

Mortgage rates in Singapore are at historic lows, making refinancing from an HDB loan to a bank loan tempting. But the switch is permanent and involves trade-offs. Understand when refinancing makes sense and when to stay put.

Sarah Chen·6 Jan 2026
  • Refinance Your Home Loan
  • Access by Cashew
  • Mortgage Eligibility Report
  • Mortgage Guide
  • Tools & Resources

    • Cashew Academy
    • Refer a Friend
    • AI Assistant
    • Calculators
    • Resources
    • Partner Banks
    • Conveyancing Lawyers
    • Properties by District
    • Property Directory
    • Managing Agents
    • Our Partners
    • Compare Brokers

    Cashew Mortgages

    • +65 8021 7460·WhatsApp
    • 400 Orchard Road #18-08
      Singapore 238875

    • Meet the Consultants
    • About Us
    • Careers
    • >_MCP
    • Contact Us

    © 2026 Cashew. All rights reserved.

    Terms of ServicePrivacy Policy